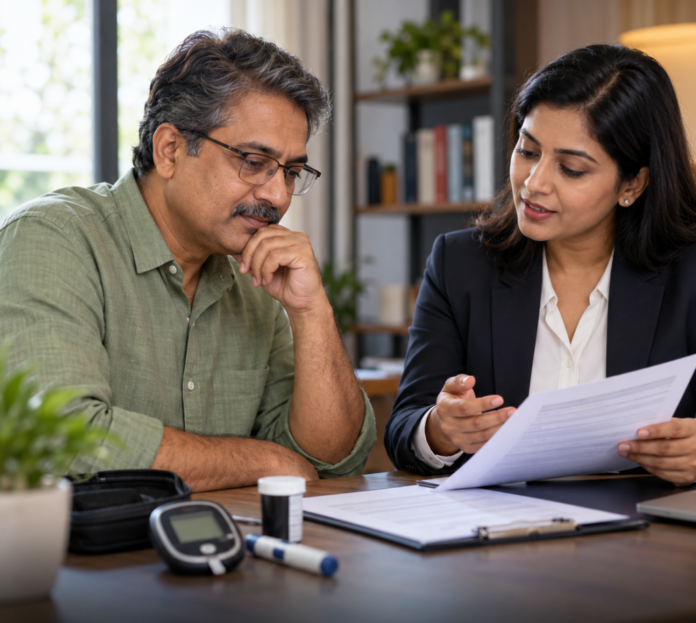
Having diabetes does not automatically mean you cannot buy term insurance. What matters is your health condition, medical history, age, lifestyle and how well your diabetes is taken care of. Insurers evaluate such details before taking a decision on whether to offer cover and at what premium.
For someone with diabetes, being open about the condition is particularly essential when applying for a policy. Being aware about the term insurance benefits and the factors that impact term insurance for diabetics can assist you in making a well-informed choice.
Term insurance benefits: Can diabetics get term insurance?
Yes, people with diabetes can usually place an application for term insurance. However, approval is not automatic. The insurer will examine your health and various other risk parameters before determining the policy terms. Let’s take a look at what this means.
1. Diabetes does not automatically rule out term insurance
One of the biggest concerns people have post being diagnosed with diabetes is if they will still qualify for life insurance. In many scenarios, the answer is yes.
Insurers do not necessarily treat every person with diabetes in the same manner. They might look at when you were diagnosed, the diabetes type you have, how well it is controlled and whether you have any related health issues.
For instance, someone whose diabetes is well managed and who on a regular basis monitors their condition might have a different evaluation from someone with poorly controlled blood sugar or diabetes-related complications.
Your age, medical history, family history, smoking or tobacco use, alcohol consumption and overall health might even be considered. So, if you are looking for term insurance for diabetics, do not assume that a diagnosis alone means your application will be turned down. The insurer will evaluate your individual circumstances.
2. Be aware of the term insurance benefits
So, why consider term insurance in the first place? The basic benefit of financial protection for your family. If the policyholder expires in the course of the policy term, the insurer makes payment of the death benefit to the nominee, subject to the policy terms and conditions.
This payout can assist the family in managing essential financial commitments, such as:
Household expenditures
Outstanding loans and other liabilities
Children’s education
Future financial goals
Day-to-day living expenses after the loss of income
Term insurance is usually designed to provide life cover for a specified period. Unlike investment-linked or savings-oriented insurance products, its basic purpose is protection.
For a person with diabetes, this protection can be particularly relevant as planning for the financial future of the family should not stop because of health condition. This said, the correct cover amount must be based on your income, liabilities, financial goals, and the needs of your dependants.
3. Your diabetes management can impact the assessment of insurer
When you place an application for term insurance, the insurer might ask questions regarding your diabetes and overall health. Based on your age, health details, and the underwriting process of insurer’s underwriting process, you might also be asked to undergo medical examination.
The insurer might consider factors such as:
Your diabetes type
Diagnosis age
Current blood sugar levels
Medication or treatment being followed
Prevailing health complexities
Blood pressure and other health conditions
Lifestyle habits
Medical history
Do not hide your diabetes or provide incomplete information just to try to get a lower premium. It can create problems later on in life, particularly when the insurer is assessing a claim. In place, provide accurate info and the medical documents requested. If your condition is well managed, keeping relevant medical reports as well as treatment records handy can make it easier to provide the required info.
The insurer then makes use of the info available to evaluate the risk and determine if the policy can be offered and on what terms.
4. Your premium may be different if you have diabetes
Here is where many applicants have questions. Will having diabetes increase your term insurance premium?
It can. Since diabetes might increase certain health risks, an insurer might consider a diabetic applicant to have a higher risk than an otherwise similar applicant without the condition. The premium offered can therefore be higher, based on the health profile of the individual and underwriting assessment.
But there is not one fixed premium for everyone with diabetes. Two people with the same age and income could receive different quotes as their medical history, diabetes management, lifestyle and other risk parameters might vary. Here is why it is worth comparing policies rather than assuming that the first quote you get is your only option.
You must also look beyond the premium. Check out the sum assured, policy term, exclusions, claim requirements and other policy conditions before making any decision.
5. Be honest and compare your options before buying
When purchasing term insurance for diabetics, accurate disclosure is one of the most essential things you can do.
Tell the insurer regarding your diabetes, medication, previous medical conditions, and any other info asked for in the application. Do not leave out a condition because you think it might increase your premium.
Why? Because your application becomes part of the info used to assess the policy. If important health information is not disclosed, it could potentially result in complications in the course of claim assessment, based on the circumstances and applicable policy terms.
It is also a good idea to understand the policy before signing up. Ask yourself:
How much life cover does my family require?
How long should the policy continue?
Can I afford the premium comfortably?
Are the policy terms and exclusions clear enough?
Have I disclosed my health info in an accurate manner?
What documents or medical tests does the insurer need?
Taking slight time to answer such questions can assist you in choosing cover that is apt for your circumstances.
What can diabetics do before applying for term insurance?
In case you are planning to purchase term insurance and have diabetes, a little preparation can make the process easier.
Begin by gathering your recent medical records as well as details of your current medication. Being aware about your medical history can assist you in providing accurate info when completing the application.
Also, it is useful to understand your financial requirements before deciding the sum assured. Think about the family’s present expenses, outstanding loans, children’s education and other long-term commitments.
Most importantly, do not wait until you have an urgent need for life cover. Beginning the process earlier might give you more options because age is even an essential factor in life insurance underwriting.
And remember, managing diabetes is not just about insurance. Following the advice of your doctor, taking prescribed medication and maintaining healthy lifestyle habits are essential for your total wellbeing.
Ending note
Diabetes does not necessarily close the door on term insurance. You can still explore life cover, but the insurer will evaluate your health condition and other risk parameters before deciding the terms.
The term insurance benefits remain the same: helping safeguard the financial future of your family if you are no longer around to provide for them. For those considering term insurance for diabetics, the most sensible approach is to disclose your condition transparently, understand how it might impact the premium and compare the available policy options.
Do not allow the fear of rejection to stop you from exploring your choices. Check out your financial needs, understand the cover you require and speak to the insurer regarding your health condition. The correct policy is one that gives your family meaningful financial protection while fitting comfortably within your budget.
This article was originally published by Antigua News Room. Read the original article here: Term insurance benefits: Can diabetics get term insurance in India?.